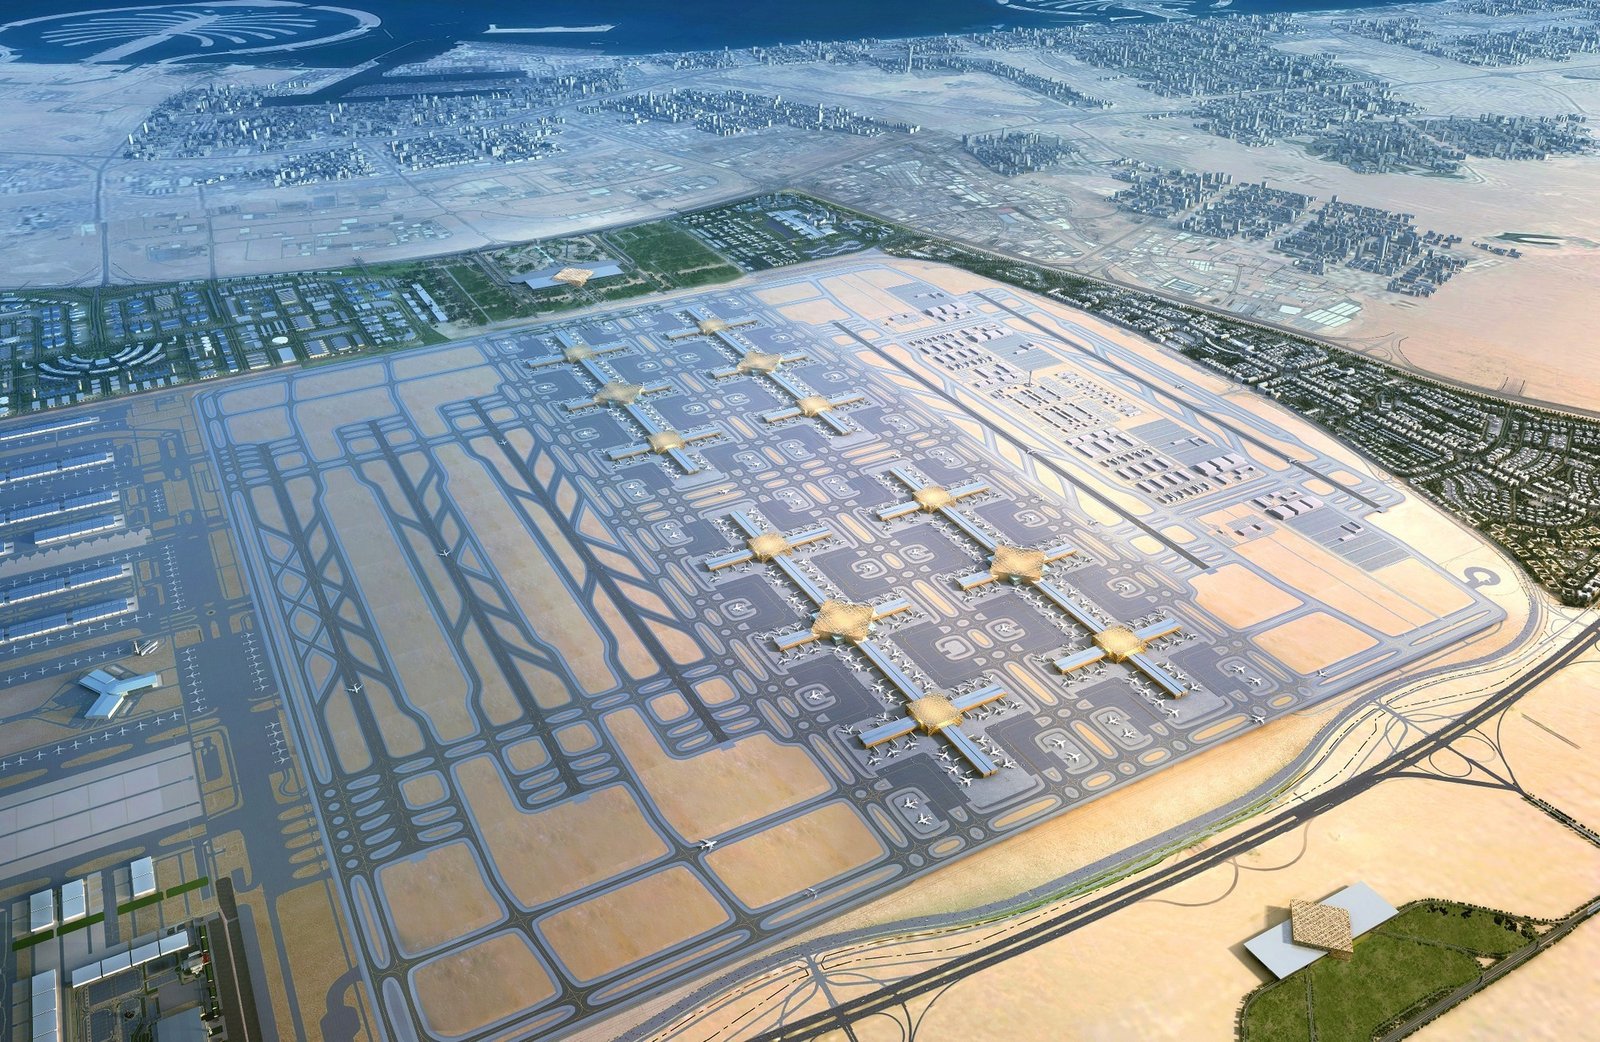
Dubai South is picking up speed for a boring, durable reason: it sits next to Al Maktoum International Airport (DWC) and Expo City, and the city’s 2040 plan keeps pushing jobs and infrastructure toward exactly this corner. A Dhs 128 billion airport program, the Route 2020 Metro to Expo, planned Etihad Rail passenger service, free-zone advantages, and relatively affordable entry prices all compound in the same place. That combination is where real rental yield and long-run appreciation tend to come from.
I have walked this area more times than I can count. Not every corner, but enough to notice the pattern investors like: good bones now, bigger things loading.
Location and connectivity
Next to a once-in-a-generation airport expansion
Dubai South borders DWC, the site of a Dhs 128 billion upgrade that will ultimately handle up to 260 million passengers and become the world’s largest airport by capacity. Officials have signalled a staged migration of operations from DXB over the next decade. That scale, and the jobs and logistics that follow it, anchors housing demand in the surrounding districts. Aviation is not a theoretical driver here. DXB just posted record traffic, and the emirate keeps doubling down on aviation as a growth engine, which is useful context when you are underwriting a five to ten-year hold.

Expo City: from world expo to permanent 15-minute city
On Dubai South’s doorstep, Expo City has been repurposed as a sustainable mixed-use district: offices, residences, schools, R&D, retail. It brands itself the new centre of Dubai’s future, and it keeps the Expo legacy alive through an innovation-first master plan and a UAE-first Green Innovation District. If you believe in jobs-first demand, that is your nucleus.

Metro now, national rail next
- Dubai Metro (Route 2020): the Red Line extension already connects Dubai Marina and Sheikh Zayed Road to Expo City. Short, predictable commutes, which is an underrated perk for tenants.
- Etihad Rail (passenger): the inter-emirate service is tracking toward launch, with route plans showing a Dubai station near Jumeirah Golf Estates and a stop close to Al Maktoum Airport. Timelines evolve, but the direction of travel, literally, is clear.
- Highways: Dubai South sits between Dubai and Abu Dhabi with direct access to Emirates Road (E611) and Sheikh Mohammed bin Zayed Road (E311). Assume roughly 30 to 45 minutes to Downtown in typical traffic.

Resilience and citywide infrastructure spend
After the 2024 storms, Dubai launched Tasreef, a Dhs 30 billion rainwater drainage upgrade running 2024 to 2033, with early phases focused on southern corridors including Expo, Jebel Ali, and DWC. Investors overlook this, but resilience spending exactly where new growth is clustering matters to long-term value.
Connectivity snapshot
| Link | Current status | What it means for residents and investors |
|---|---|---|
| Route 2020 Metro to Expo City | Operational | Predictable commutes, easier leasing to non-drivers |
| Etihad Rail (passenger) | Announced, route revealed, phased rollout | Long-run inter-emirate access, demand uplift near stations |
| DWC expansion | Approved, multi-year buildout | Jobs, logistics scale, air connectivity, a structural demand driver |
| Tasreef drainage program | 2024 to 2033 | Citywide resilience, southern areas prioritised early |
Drive times: roughly 25 to 35 minutes to Dubai Marina, 35 to 50 to Downtown outside peak. Always confirm at your actual viewing time.
Economic and business advantages
Free-zone DNA, and why it matters for housing
Dubai South and the districts around it offer the classic UAE free-zone stack: 100% foreign ownership, profit repatriation, customs and tax relief, streamlined setup. Expo City markets flexible business hub packages and visas, drawing startups, SMEs, and corporate satellites. Talk to HR directors and you hear the same theme. When onboarding ramps up, the nearby rentals fill up.
Jobs follow infrastructure, tenants follow jobs
Expo City’s shift from a temporary event site to a permanent innovation campus, with education, sustainability programs, and R&D, supports stable white-collar employment right on Dubai South’s doorstep. Pair that with the airport and logistics ecosystem and you get a diversified tenant base, not just seasonal short-term demand.
Yields today, optionality tomorrow

No one can promise straight-line growth. Fitch has warned about a possible mid-cycle price correction as supply normalises. But areas with low starting prices and big catalysts usually defend yields better in down years and compound faster in up cycles. Dubai South fits that playbook: affordable tickets, improving transport, and institutional-grade anchors in the airport and Expo City.
Honest version: yes, there can be construction views, dust, and a wait for retail to catch up. That is also where early-cycle returns tend to live.
What you feel on the ground

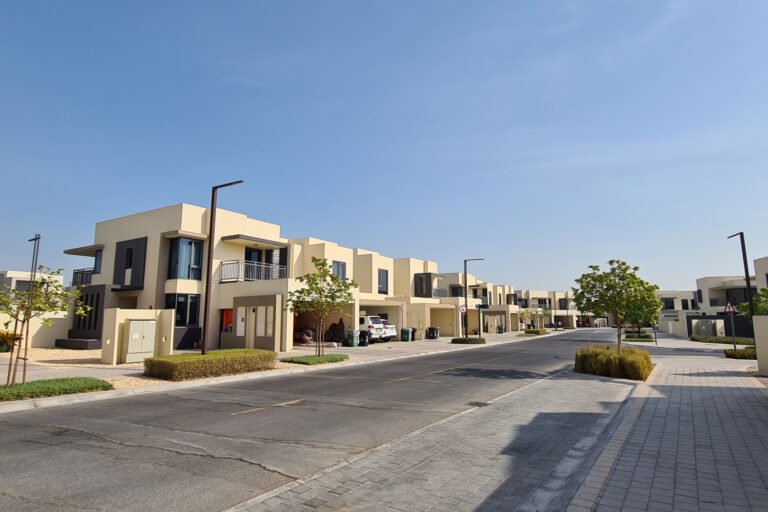
You can already see the scaffolding of a complete neighbourhood: new schools, parks, groceries, clinics, mid-rise blocks that do not try too hard. The main draws are affordability and space, with a family-friendly public realm and pragmatic access to the city’s west and south corridors. It is not Downtown Dubai, and that is the point.
Against the brand-name areas
- Price: typically lower entry than Dubai Marina, Downtown, and parts of Dubai Creek Harbour, which keeps gross yields competitive and widens your tenant pool. Always check current AED per sqft per project.
- Quality of life: quieter, greener, newer utilities, fewer bottlenecks, growing retail that is not complete yet.
- Volatility: early-cycle districts can move faster both ways. Smart underwriting uses conservative rent assumptions and a three to four-year hold to let the catalysts land.
Value vs convenience
| Factor | Dubai South | Dubai Marina | Downtown Dubai |
|---|---|---|---|
| Typical entry price (1 to 2BR) | Lower | Higher | Higher |
| Metro access | Route 2020 to Expo, buses | Red Line stations | Red Line stations |
| Highway reach | E611 / E311 | SZR | SZR / Al Khail |
| Retail and amenities | Growing | Mature | Mature |
| Yield profile | Often higher gross yields | Lower gross yields | Lower gross yields |
| Who it suits | Value and growth investors, airport/Expo workers | Lifestyle and short-let | Professionals wanting center-city |
Policy alignment means tailwinds
Dubai South sits neatly inside the Dubai 2040 Urban Master Plan, which concentrates growth around five urban centres and emphasises transit-oriented, 20-minute-city living. Expo and Dubai South are a core node in that pattern, visible in everything from Metro and rail planning to citywide green and social infrastructure goals. Opinions differ on timing, but the Etihad Rail network and the broader mobility stack are being designed as a system, which matters for absorption beyond the first wave of buyers.
What it means for different buyers
- Yield-first: 1 to 2BR units within walking or bus range of Expo Metro. Favour layouts that rent easily, balconies, 1.5 baths.
- Appreciation-first: plots closest to future rail and airport interfaces. Be early in phases with clear handover dates.
- End-users with airport ties: short commute, quieter blocks. Check school runs and retail timelines honestly.
- Short-let operators: mind the STR licensing rules and seasonality. Proximity to Expo events still counts.
Prices and yields
Indicative averages, Q1 to Q3 2025:
| Area | Avg price psf (AED) | Notes on data | Typical gross yields |
|---|---|---|---|
| Dubai South (overall, mixed projects) | ~1,019 | Q1 2025 resale report (apartments) | ~6 to 8% (project-dependent) |
| Emaar South (within Dubai South) | ~1,437 (apartments) | Transaction analytics (rolling) | ~6.0 to 6.2% (2 to 3BR avg) |
| Dubai Creek Harbour (benchmark, not adjacent) | ~2,388 (apartments) | Transaction analytics (rolling) | ~5 to 6% (mix) |
Yields vary by bedroom mix, view, handover timing, and furnishing. The Dubai South Q1 2025 resale average of AED 1,019 psf comes from a Totality Real Estate report. Chestertons’ 2025 Emaar South guide pegs 2 to 3BR apartments at roughly 6.2% gross, and several brokerage round-ups show Dubai South at 6 to 8% depending on unit type. Keep in mind asking rents and achieved rents can differ. As a tailwind, Hamptons’ March 2025 review flagged sharp year-on-year rent growth in Dubai South and Al Furjan on the back of infrastructure and metro effects.
Reality check: numbers move. Before you sign an SPA, pull fresh comps from the last 90 days and a rent roll for the exact stack and floor you are targeting.
The demand math, briefly
- Airport: the DWC program targets 150m+ passengers in early phases, up to 260m later, plus five runways and around 400 gates. Jobs and logistics intensity raise absorption in the immediate catchment.
- Expo City: a free-zone, innovation-led 15-minute city with school, work, retail, and 180+ business services keeps weekday footfall local and rents sticky.
- Connectivity: Route 2020 already runs to Expo, and Etihad Rail is advancing toward a Dubai alignment near DWC and Expo. Long-duration, but directionally potent.
- Resilience: the AED 30bn Tasreef program focuses heavily on the southern corridor, a quiet but meaningful risk reducer.
Where the value clusters
- Walkable to Expo City, short bus ride to Route 2020: easiest to lease to non-drivers. Studios and 1BRs are the workhorses.
- Golf-adjacent Emaar South (Urbana, Golf Views): family renters, slightly higher psf, steadier tenant profiles. Yields hold if you buy the right layouts.
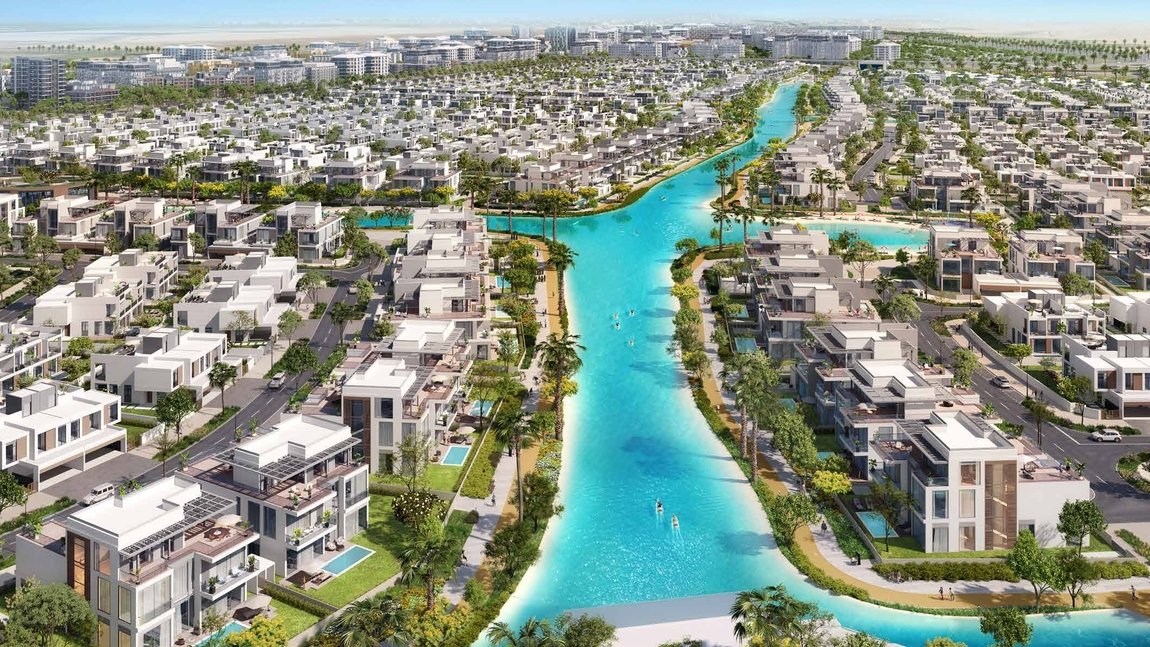
- South Bay and The Pulse corridors: early-cycle pricing with community retail catching up. Upside linked to DWC milestones.
Head-to-head
| Factor | Dubai South (mixed) | Emaar South (inside Dubai South) | Dubai Creek Harbour |
|---|---|---|---|
| Positioning | Value and growth near DWC/Expo | Master-planned, golf-adjacent, family-tilted | Premium waterfront, nearer old CBD |
| Avg apt price/psf | ~AED 1,019 | ~AED 1,437 | ~AED 2,388 |
| Tenant base | Aviation, logistics, Expo, SMEs | Families, expat professionals | Finance and creative sectors, mixed |
| Transit | Route 2020 nearby, future rail | Same, car-first, bus links | Road links, Metro at Creek stations |
| Yield profile | 6 to 8% (by mix) | ~6% (2 to 3BR focus) | ~5 to 6% |
| Risk | Construction cycles, retail lag | Lower volatility inside brand masterplan | Pricey entry, lower gross yields |
Free-zone and visa notes
If you plan to set up a business alongside owning property, useful for visas and cash-flow operations, you have two adjacent free-zone options:
- Dubai South Free Zone: 100% foreign ownership, streamlined licensing, visa services through the Dubai South authority. Corporate tax treatment depends on UAE FTA rules and whether income qualifies, so get professional advice.
- Expo City Dubai Free Zone: flexible business hub packages, freelance permits, short-term operation permits from one day to 12 months, and more than 180 services under the Expo City Dubai Authority.
Risk and timing matrix
| Risk | What it looks like here | Mitigation |
|---|---|---|
| Market cycle | Independent houses warn of mid-cycle correction risk (Fitch floated roughly -15% into 2026), especially as large new supply lands. | Favour rent-defensible units, model base rent -5%, extend your hold. |
| Construction and retail lag | Patchy retail in pockets, dust and changing views during build-out. | Buy near existing schools and groceries, lock developer handover dates with penalties. |
| Liquidity at exit | New supply can mute resale velocity. | Target sub-6% vacancy buildings and popular stacks, list with pro photos 60 to 90 days ahead. |
| Speculative psf creep | Later phases can list too high vs comps. | Walk the comps, insist on net-to-owner yield at or above your hurdle at today’s rents. |
| Transport timelines | National rail timing is phased. | Underwrite as option value, do not rely on it to make a deal pencil. |

Unit-level checklist, so you don’t overpay for “new”
- Yield anatomy: studios and 1BRs near Route 2020 stations tend to lead gross yield, while 2 to 3BRs in Emaar South lead lease stability (Chestertons calls out 2 to 3BRs at 6%+).
- Layouts: 1.5-bath 1BRs, balconies, and straight walls rent faster. Corner 2BRs with split bedrooms keep families.
- Charges: service-charge discipline matters in newer districts. Verify AED per sqft and the reserve-fund policy.
- Noise and flight path: check approach patterns to DWC as operations scale. Protection zones exist, but do an evening site visit. Dubai Airports.
- Handover and snag: demand a snag report and defect-liability timelines. In early cycles, a good property manager saves your weekends.
Value vs convenience short-list
| Sub-area | Why it is on the radar | What to verify |
|---|---|---|
| Expo-adjacent blocks | Walkability to Route 2020, weekday footfall | Actual door-to-platform time, grocery and school distance (RTA) |
| Emaar South (Urbana, Golf Views, Parkside) | Brand, golf, family demand, mid-market rents, steady yields | Latest psf vs Bayut and Property Finder transactions |
| South Bay / The Pulse | Early pricing, lifestyle amenities planned | Retail opening schedule, HOA budgets, service charges |
| Creek Harbour (benchmark) | Premium comp set, strong waterfront brand | Psf premium vs your yield target |
A tax caveat: free zones advertise attractive regimes, but UAE Corporate Tax applies at 0% only to qualifying income under FTA guidance. Non-qualifying income can be taxed. Get custom advice before structuring.
The buying playbook
Step 1: Define the objective, and write it down. Are you after income (a steady 6 to 8% gross in today’s conditions) or optionality (being early near an airport and innovation hub)? If you want both, fine, just rank them. It is oddly helpful when two similar units have you second-guessing.
Step 2: Micro-map your commute and your tenant’s. Walk from the likely buildings to the Route 2020 station at Expo City, or your bus stop. Time it. Do it once in the heat. You will feel the difference between “marketable” and “actually easy.” End-users should drive the school run at 7:30 a.m., not 11.
Step 3: Pull fresh comps, not headlines. Ask for the last 90 days of transactions, same bed and bath, similar view and floor. If there aren’t enough, widen by 10% in size and normalise to AED per psf. For rents, favour achieved leases over ambitious listings. The point is not to be perfect, it is to be anchored.
Step 4: Underwrite with three numbers and nothing cute.
- Service charges: request the latest AED per psf and the reserve-fund policy.
- Net-to-owner yield: model base rent -5%, vacancy 5 to 8%, and charges as quoted plus a 10% buffer.
- Exit liquidity: assume 60 to 90 days to find the right buyer or tenant, then be pleasantly surprised if it is faster.
Step 5: Choose the right layouts. For the investor lens, studios and 1BRs with 1.5 baths and a balcony near transit lease fastest. For the family lens, 2BR split-bedroom plans in Emaar South with a clean rectangular living room and real storage. Avoid overly creative angles and deep interior bedrooms starved of daylight.
Step 6: Handover timing and snagging. If off-plan, get milestone schedules, longstop dates, and delay penalties in writing. On handover, hire a snagging company and ask for the defect-liability period and the escalation flow.
Step 7: Financing and fees. The DLD transfer fee is commonly 4%, and off-plan Oqood registration is also around 4%. Some developers offer partial rebates, so read the fine print. On a mortgage, factor valuation fees, processing, and early-settlement rules, and test the debt-service coverage with conservative rent. For STR vs long-let, check community bylaws and permit rules before assuming short-term is allowed or wise.
Step 8: Property management. Ask for response-time SLAs, lease-up KPIs, and a fee schedule with no mystery admin lines. A good manager in a new district is worth more than a clever spreadsheet.
The truth in a growth corridor: your biggest edge is not a secret deal. It is an honest model and the discipline to walk away when the numbers do not clear your hurdle.
Short-term rental vs long-let: the back-of-napkin math
Illustrative only. Plug in your own numbers before acting.
| Metric | STR (airport/Expo-adjacent 1BR) | Long-let (same unit) |
|---|---|---|
| Assumed ADR | AED 350 | n/a |
| Occupancy | 68% | n/a |
| Gross monthly | ~AED 7,140 | AED 6,000 (annual lease ~72,000) |
| Platform / PM fees | 20% (~1,428) | PM 5 to 7% (~350 to 420) |
| Utilities, linen, etc. | AED 600 | Tenant-paid (usually) |
| Service charges (allocated) | AED 500 | AED 500 |
| Net to owner (est.) | ~AED 4,612 | ~AED 5,080 to 5,150 |
STR can outperform in event-heavy months, but it is work. In steady periods, a clean long-let often wins on stress-free net. If you go STR, price in a true operating cost and the permit steps. If you go long-let, invest in durable furniture (or none) and better photos.
1BR vs 2BR: which travels better through cycles
| Lens | 1BR near Route 2020 | 2BR in Emaar South |
|---|---|---|
| Tenant pool | Singles, couples, aviation staff, Expo/SME hires | Families, long-tenure professionals |
| Yield tendency | Higher gross (faster lease-up) | Slightly lower gross, steadier net |
| Void risk | Lower March to Nov, watch summer | Low if priced right, some seasonality ignored |
| Resale liquidity | Strong under AED 1.2m | Good if view and stack are right |
| Who should buy | Income-first investors | End-users, stability-focused investors |
End-user vs investor: decision table
| Question | If yes | Likely fit |
|---|---|---|
| Is a short commute to DWC/Expo your #1 driver? | Yes | Expo-adjacent 1 to 2BR, walkable to bus/Metro |
| Do you want schools and golf nearby? | Yes | Emaar South 2 to 3BR townhomes or apartments |
| Is maximising gross yield your main KPI? | Yes | Compact 1BR or large studio near transit |
| Do you dislike construction views? | Yes | Delivered phases with mature landscaping |
| Will you self-manage STR? | Yes | Budget real ops time or pick a pro operator |
Two buyer personas, because real life is messy
The aviation couple. Both work shifts at DWC, both hate driving. They will pay a small premium for a 10 to 15 minute door-to-platform commute and a decent gym, and they renew if noise is low and the Wi-Fi is strong. Their winning unit is a 1BR with a balcony in a building that keeps its common areas spotless.
The remote-work family. One parent travels, one works from home. They want a 2BR with a separate study nook near a school and green space, and they will accept a longer drive to Downtown if the weekends feel quiet. For them, Emaar South layouts with functional kitchens and storage simply work.

On timing
If you are buying for 2025 to 2030, you are buying into infrastructure, not after it. Prices can wobble while roads, rail, and retail mature. That is normal. The risk is not that progress takes time. It is paying a future price today. So keep your bid tethered to today’s rent and the closest comps, and let the DWC and Expo upside accrue as a bonus, not a requirement.
Developer and community roll-up
| Cluster | Primary developer / authority | Typical product | Positioning | Notable hooks |
|---|---|---|---|---|
| Emaar South (Urbana, Golf Views, Parkside) | Emaar | Apartments, townhomes | Family-tilted, golf-adjacent, steady demand | Brand pull, planned environment |
| South Bay | Dubai South | Villas, townhouses, lagoon-centric | Early cycle plus lifestyle amenities | Large masterplan depth |
| The Pulse / Pulse Beachfront | Dubai South | Apartments, townhouses | Value plus improving amenity base | Expo/DWC proximity |
| Expo City Residential | Expo City Dubai Authority | Apartments, mixed-use | Innovation campus, 15-minute city | Route 2020 access, free-zone gravity |
| Logistics / industrial fringe | Mixed | Worker housing, value apartments | Yield-first, more utilitarian | Employer demand |
On paper, these all look close. On a hot August afternoon, the ones within a true 10 to 15 minute door-to-platform of the Route 2020 station just feel easier to live in.
FAQs
Is Dubai South only interesting because of the airport?
Not only. The Expo City free zone and the wider southern-corridor investment make it more than a single-asset story. The airport is the spine, the jobs and schools are the muscles.
What is a realistic gross yield for a 1BR near Expo today?
Case by case, but 6 to 8% gross is a common range if you buy right and keep costs in line. Always model a conservative rent and a small vacancy allowance.
Are service charges high in newer buildings?
They can be, which is why you ask for the latest budget and any reserve-fund details. A well-run building with attentive facilities management often justifies a slightly higher charge.
Does Etihad Rail timing matter to my buy decision?
Treat it as option value. Great if it lands sooner, but your deal should work without it.
Is short-term rental permitted everywhere there?
No. Check community bylaws and the latest STR permit rules before planning an Airbnb strategy.
What floors or stacks rent best?
Middle floors with pleasant, open views and balanced light. Super-low floors next to construction can sit, and ultra-high floors with odd layouts sometimes underperform.
End-user here: will I feel far from the city?
Some days, yes. Other days the lack of congestion feels like a small luxury. Metro and highways help, just be honest about your lifestyle.
Are developers offering fee rebates?
Occasionally, part DLD coverage, payment plans, or furnishing packs. Read every clause and compare the all-in.
Townhouse or apartment for long-term value?
Townhouses suit families and can hold value well. Apartments close to transit usually win on liquidity.
What is one mistake to avoid?
Basing your price on future connectivity rather than present rents and actual comps.
The bottom line
Dubai South is rising for reasons that do not depend on hype: an airport expansion measured in runways and gates, a recycled world expo turned living district, and a city plan that keeps pushing jobs and infrastructure south and west. Is it finished today? No. Some corners still look at cranes. That is how a lot of Dubai’s best stories started. If you buy here, buy for what it is now, the rents, the commutes, the schools, with the humility to treat future rail as a bonus rather than a baseline. Keep your underwriting dull, your photos excellent, and your service-charge questions sharp.
More reading
- Dubai 2040 Master Plan, impact on real estate
- Off-Plan in Dubai: Goldmine or Death Trap?
- Dubai Property Manager: Compare Options
- How Dubai Became the Most Liquid Property Market in the Middle East
Yield-first? Turn capital into cash flow. Get a 15-minute Dubai South yield plan: three comps, today’s rent, net-to-owner math. Book a free consultation.