I have watched a few of these cycles up close, and this one behaves differently. It is broader, more deliberate, and frankly more disciplined than the ones I remember. Not flawless, nothing is, but the top end is holding up far better than most people expected.
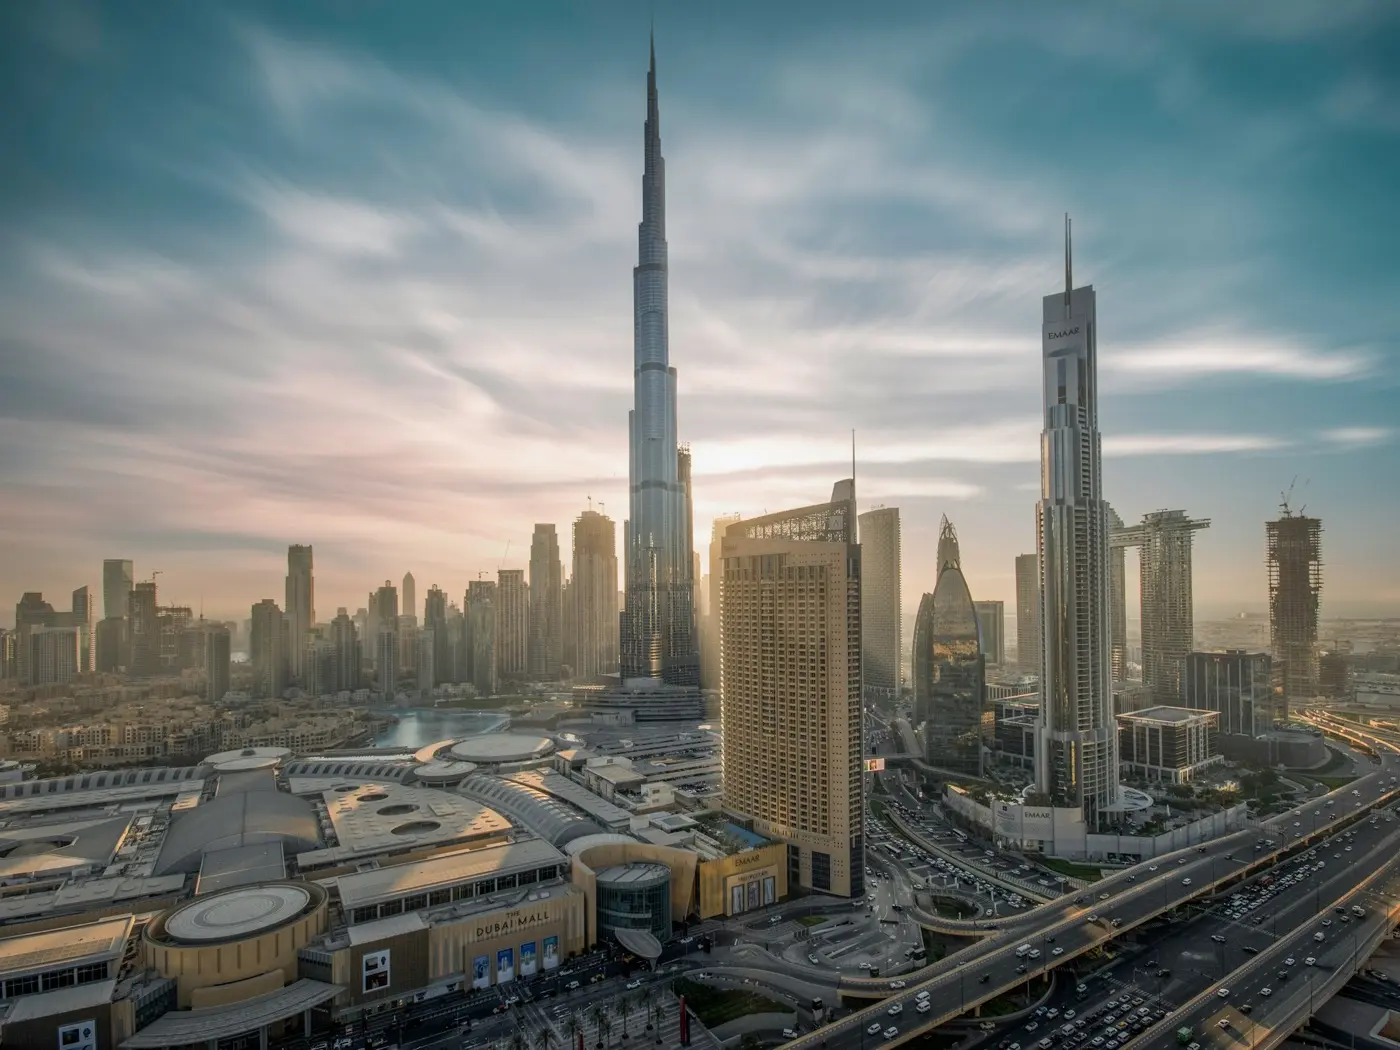
Dubai luxury has always drawn a crowd. What is happening now is not just the next turn of an old cycle. It is bigger, more international, and more strategic. Waterfront villas on the Palm, branded penthouses in Downtown, ultra-modern homes going up around District One: 2025 is the year Dubai settles into the top tier of the world’s luxury property markets, for lifestyle and for protecting capital both.
International demand is the story. High-net-worth and ultra-high-net-worth buyers come for quality of life, residency certainty and tax efficiency, then stay for asset quality and liquidity. At the prime end, price growth keeps outrunning most global peers. Prime values rose about 5% in H1 2025, and Dubai ranked among the top three markets worldwide for luxury price growth, per Savills’ World Cities Prime Residential Index.
At the ultra-prime level the numbers have gone from exceptional to routine. Deals above US$10m hit an all-time quarterly record of US$2.6bn in Q2 2025, after the strongest Q1 on record at 111 sales above $10m. This is a pipeline, not a spike. Dubai keeps leading the world in $10m+ home sales, on the back of visa policy, brand-grade product and lifestyle infrastructure working together.
And the breadth is real. Resale, ready ultra-prime and branded off-plan all sit inside a market that recorded AED 431bn in transaction value in H1 2025 and AED 761bn across 2024. Wide base, deep top. You do not see that combination often.
Why this boom is different, in short
- Policy tailwinds. Golden Visa pathways and clear residency rules take the risk out of relocating for globally mobile families.
- Tax and capital preservation. Zero income tax and a hard-asset hedge in a politically neutral hub.
- Infrastructure and brand ecosystem. Airports, schools and healthcare that compete with the best, paired with hotel-grade branded residences.
- Genuinely finite prime stock. Waterfront, golf-course estates and trophy penthouses are limited by geography and planning, not by how many projects a developer can announce.
The longer version is where it gets useful, so let me take it apart section by section.
Record transactions and rising benchmarks
The $10m+ tier has moved from newsworthy to normal. In Q2 2025, deals above US$10m reached US$2.6bn, up 37% quarter on quarter and 63% year on year. Q1 2025 posted 111 such transactions, the strongest first quarter on record, and Q4 2024 held the previous high. These are not speculative reservations. They are funded, often cash, and they tend to close fast, sometimes off-market.
At the prime tier, Dubai ranked top three globally for price growth in H1 2025. Savills puts it down to sustained demand against tight prime supply, with capital values up roughly 5% in six months. Visa programs and regulatory clarity keep liquidity high, and the transaction base is deep: 125,538 transactions in H1 2025, up 26% year on year.
One honest caveat, because balance is healthy. Some analysts see strain building in the lower-end, highly speculative segments as a large wave of apartments completes through 2027. That is a different market from trophy and prime stock, but it exists in the wider picture and it deserves a mention.
The branded residence effect
You can argue taste all day. You cannot argue service consistency. Branded residences, think Ritz-Carlton, Four Seasons, Armani, Dorchester Collection, Bulgari, even the automotive brands, carry a known service standard and a level of global trust. That counts for a lot when a buyer is closing from London or Mumbai and wants certainty without weeks of diligence on the ground.
Savills tracks steady global growth in branded residential pipelines into 2024 and 2025, and Dubai sits among the leaders for depth and range of branded stock. Local analyses count tens of thousands of branded units now in Dubai, with new projects launched in H1 2025 and a clear shift toward larger tickets at the ultra-prime end. The short version: the brand premium, often around 20 to 30% over comparable unbranded stock, is increasingly earned through service, management and a cleaner resale story.
Who is buying, and why the profile changed
The nationality mix is properly global now. European, Indian, Russian, British, German, Nigerian, Chinese and Egyptian buyers, plus Switzerland, Turkey, South Africa and, increasingly, North America. Motivations fall into three buckets:
- Primary lifestyle relocation, for schools, healthcare, safety, travel connectivity and climate.
- Capital preservation and diversification, a politically neutral, tax-efficient base for holding real assets.
- Yield plus use, short-stay income while they travel, personal use in peak season.
A telling number: Knight Frank’s Destination Dubai 2025 found 83% of surveyed global HNWIs interested in buying land in Dubai to build custom homes. That points to a structural tilt toward end use over pure speculation, which is a healthier kind of demand.
Supply at the true-prime end is finite, and tightening
Developers launch weekly, that part is true. But the finite set of irreplaceable locations, the Palm Jumeirah waterfront, Jumeirah Bay Island, Emirates Hills, top-stack Downtown and Burj views, low-density Dubai Hills Estate, cannot be manufactured. In those pockets ready inventory is constrained, and once end users or family offices lock assets up, churn drops. That is why sellers hold more pricing power in the trophy sub-markets now than they did five years ago. It is not universal, it is highly sub-market specific, and you can see the tightness in the prime price indices and the repeated quarterly records above $10m.
The luxury rental engine
Sales are only part of it. High-end rentals, particularly furnished penthouses and modern villas, are carried by executives, founders and location-flexible professionals who would rather rent before they buy. Short-stay luxury occupancy stays strong around major events and peak seasons, and yields in selected luxury stock can reach mid-single to low-double digits, depending heavily on the property and the operator. It is specific enough that underwriting matters. We tend to model conservatively, then test how it holds up across operator quality and seasonality.
Why lifestyle keeps landing in the financial models
Capital follows safety. Lifestyle follows both. Zero income tax, a useful time zone, airport connectivity, healthcare and education are not soft factors in 2025, they are decisive. Where luxury elsewhere has become politicised or constrained, Dubai stays straightforward: buy, sell, rent, renovate, with clear rules and fast processes. That clarity, next to genuinely top-tier leisure and hospitality, keeps global families choosing Dubai as a primary or secondary base. The Savills and DLD trends line up with what I see day to day: more end users, larger tickets, fewer forced sellers in the prime sub-markets.

Dubai against other global luxury hubs
| Factor | Dubai (2025) | London | New York |
|---|---|---|---|
| Income tax on individuals | 0% | Progressive | Progressive |
| $10m+ sales momentum (recent trend) | Global leader; record Q2 2025 volume | Deep market; higher taxes and levies | Deep market; higher carrying costs |
| Branded residences ecosystem | Extensive, fast-growing | Select, established | Select, established |
| Prime price growth (H1 2025) | About +5% | Mixed | Mixed |
| Visa and residency pathways | Golden Visa, clarity | Complex | Complex |
Notes: the comparative cells are directional, drawn from policy frameworks and recent trends reported by Savills, Knight Frank and DLD. Always underwrite at the sub-market level.

FAQ
- Is Dubai still leading the world for $10m+ home sales? Q2 2025 hit a record US$2.6bn, so yes.
- Are prime prices still rising? About 5% growth in H1 2025 puts Dubai in the top three global markets.
- What is the biggest risk? Not at the ultra-prime tier. The risk clusters in oversupplied apartment segments as completions ramp through 2027.

Branded versus unbranded: what actually justifies the premium
| Dimension | Branded residence | Non-branded luxury |
|---|---|---|
| Service and operations | Hotel-grade, standardised | Varies by owner or association |
| Resale narrative | Global brand trust; easier for cross-border buyers | Highly building-specific |
| Price premium | Often around 20 to 30% | Benchmark |
| Rental appeal | Higher ADR potential in short-stay | Variable |
| Risk | Operator dependence | Association or owner dependence |
Sources: Savills on global branded residences, local Dubai transaction tracking, and brokerage experience.
Palm Jumeirah, Jumeirah Bay and Dubai Hills: three very different primes
People ask me which luxury area is best. It is the wrong question, but a fair one. The right question is: best for what outcome? Because these three headline markets deliver value in completely different ways.
Palm Jumeirah: striking, liquid, still scarce
The Palm is the postcard, the place where you know exactly what you are buying. Water, skyline, and if you choose right, sunset drama you cannot recreate inland. The best villas feel private even when they are not, and the best apartments live like villas in the sky. Serious buyers here split between end-use families and collectors hedging across global waterfronts, and both care about the same things: approach roads, beach quality, orientation and build integrity.
What matters most right now, in my view:
- Orientation and frontage outweigh raw built-up area.
- Renovation pedigree, meaning design, contractor and materials, increasingly sets resale speed.
- Quiet stacks in the prime towers can surprise you on long-term livability.
If you want to see current showcase stock or quietly check off-market inventory, start at https://totalityestates.com/.
Jumeirah Bay Island: trophy, low-churn, brand-adjacent
JBI is more club than neighbourhood. Yes, it is villas and plots, but it is also the Bulgari Hotel next door, yacht berths, and a sense that everyone there knows why they are there. Transactions come in lumps, long quiet stretches then a headline, and supply is genuinely constrained. When these trade, they trade decisively. Weigh JBI against the Palm and you are really comparing rarity against striking familiarity. Rarity tends to win late in a cycle, provided you stay disciplined on design and execution.
If you want a valuation or a discreet buy-side brief, reach us at https://totalityestates.com/contact.
Dubai Hills Estate: family utility with prime credentials
Dubai Hills, especially golf-front and the more private streets, is the city’s practical luxury choice. Parks, schools, access. It is where buyers who could live anywhere actually choose to live once the routine, the school runs, the commute, the grocery shop, matters more than the postcard. The best plots pair park adjacency with real setback depth. And in my view, feel free to disagree, a properly finished move-in-ready home here deserves a meaningful premium over developer-standard interiors. People underestimate both the cost and the friction of doing that work later.
If you want before-and-after case studies and how that affects price and days on market, say so. We keep private comps for clients at https://totalityestates.com/.
Fit to buyer profile
| Buyer goal | Palm Jumeirah | Jumeirah Bay Island | Dubai Hills |
|---|---|---|---|
| Waterfront “wow” | ★★★★★ | ★★★★☆ | ★☆☆☆☆ |
| Rarity / club feel | ★★★★☆ | ★★★★★ | ★★★☆☆ |
| Everyday family utility | ★★☆☆☆ | ★★☆☆☆ | ★★★★★ |
| Liquidity (broad global recognition) | ★★★★★ | ★★★★☆ | ★★★★☆ |
| Renovation tolerance needed | Medium to high | High (for plots and rebuilds) | Low to medium |
Stars are directional, not absolute. Sub-streets and build quality can swing the result.
How to underwrite a branded residence in 2025 without overpaying
Branded residences are not just a logo on the door. They are an operating system for living: service, standards and a resale story. That said, the premium is not automatic. You still have to underwrite like an adult.
The four lenses I use
- Brand-operator fit. Not every brand belongs in every location or building type. A resort brand jammed into a dense urban stack can feel off. Check whether the service DNA matches the daily use case. If you will live there most of the year, hotel-heavy programming can feel intrusive rather than helpful.
- HOA and FF&E economics. Not fun, but read the documents. Service charges, the sinking fund and FF&E refresh cycles decide your five-year cost. I often build a shadow P&L for clients: one line for fixed charges, one for realistic refresh capex, and one for actual household operations, meaning staff and utilities.
- Elevator logic and stacking plan. The best lobby in the world does not fix bottlenecks. Study lifts per key, separate service and back-of-house routes, and how guest and resident circulation are kept apart. If you feel it at 4pm on a Sunday, imagine it at 8pm during Eid.
- Exit story, to whom and why. When you resell, are you telling a brand story or a unit story? The best assets do both. If your only edge is the brand, you are overexposed to the next branded launch. If your unit also has line-of-sight views, corner glass, ceiling height or terrace depth, you own something that is hard to replicate.
Branded residence diligence checklist
- Confirm the operator agreement length, termination rights and handover standards.
- Map services included against those “available at charge”, and the actual charge.
- Inspect noise pathways: mechanicals, food and beverage, valet.
- Ask for historical service-charge schedules and the forecasting method behind them.
- Verify valet capacity and resident parking ratios.
- Benchmark rental demand by season and length of stay, if that is part of your plan.
If you want help unpacking a specific brochure or MOU, we do it daily at https://totalityestates.com/contact.
Off-plan or ready in 2025 to 2027: which makes sense now
I will admit a bias. For genuine prime or trophy outcomes I like ready or near-ready assets, provided they are design-forward and properly built. The good ones get rarer every quarter. Off-plan can still work when the brand or operator is credible, the location is irreplaceable, and the payment plan plus the opportunity cost make sense against your balance sheet.
| Criterion | Off-plan luxury | Ready prime |
|---|---|---|
| Capital outlay profile | Staged (developer plan) | Lumpier (completion and close) |
| Certainty of product | Render risk; spec drift possible | What you see is what you get |
| Time to use or rent | 24 to 36 months typical, sometimes longer | Immediate |
| Price discovery | Launch premiums; herd risk | Comps transparent; condition-driven |
| Customization | Some pre-handover options | Post-purchase renovation (time and cost) |
| Liquidity | Can be narrow pre-handover | Broad if truly prime or unique |
One rule I keep repeating: if the only reason you like an off-plan launch is the payment plan, you probably do not like the real estate enough.
A step-by-step buying playbook for HNW and UHNW buyers
You can do this haphazardly, or you can treat it like a surgical process. I prefer surgical.
1. Define the non-negotiables before you see anything
- Life setup: schools, commute patterns, weekend habits.
- Aesthetics: warm modern, classic, hotel-residential.
- Deal tolerances: renovation yes or no, construction risk yes or no.
- Tax and residency: Golden Visa plans, family structure, holding-company questions.
Write it down, then hand it to the advisor actually doing the work at https://totalityestates.com/contact.
2. Build a shortlist with red-flag columns
Take the emotion out by scoring view corridors, noise sources, lot geometry, service charges, HOA health and exit audience. When two assets tie, the one with the cleaner exit story usually wins.
3. Walk twice, measure once
The first visit is for feel, the second is for facts. On the second walk bring a noise meter, an orientation or solar app, and a simple laser measurer for terrace depths, ceiling heights and setbacks. Reality is often 5 to 10% off the brochure.
4. Paper it like a professional
- Make sure the MOU cleanly reflects inclusions (FF&E lists), snagging, penalties and closing logistics.
- For off-plan, scrutinise spec schedules, variation clauses and handover triggers.
- For ready, insist on a snagging list with completion remedies, not friendly promises.
We keep checklists and draft language you can adapt. Ask and we will share them via https://totalityestates.com/.
5. Plan the first 90 days after close
- Immediate works (paint, flooring, AV) sequenced around contractor access windows.
- Insurance and smart-home setup in week one.
- Operator or house-manager onboarding if you will rent seasonally.
- Residency and banking appointments folded into your stay.
6. Own the exit from day one
Even if you never sell, act like you will. Archive as-builts, warranties and photo logs of every improvement. Keep a digital home manual. When the time comes you will command a premium simply because the story is clear and verifiable.
Common mistakes I see, even from experienced buyers
- Confusing loud luxury with livable luxury. A jaw-dropping lobby gets old if the lift waits do too.
- Chasing newness over placement. A second-best location rarely catches the first-best over time.
- Underestimating operational friction. Service charges are one line; household operations are three.
- Falling for the brand and ignoring the stack. The line you buy on, and the neighbours above and below, still matter.
- Skipping the private, off-market look. Some of the best assets never hit the portals. Get an advisor who is called before the photographer is.
Micro-signals that a building is genuinely well run
- Back-of-house smells clean, not perfumed. That is discipline, not staging.
- The resident WhatsApp group is a little boring. Drama-free is a feature.
- You see maintenance staff in the morning, not only in the evening. Preventive, not reactive.
- Noisy mechanicals are properly insulated. Stand in the corridor and listen. If you hear a whine, imagine it at 2am.
If you want a quiet building-ops walk-through, we do them. Reach us at https://totalityestates.com/contact.
Two quiet-edge strategies if you want to be early
- Corner-case view logic. Everyone wants the full view. But partials, angled water, framed skyline, layered park, often feel more intimate and photograph better, and those lines can be underpriced relative to how they actually live.
- Renovation-ready homes. Find places where the layout is right but the finishes lag by one design cycle. You can modernise the kitchen, baths and lighting in 60 to 90 days, and the gap between as-is and editorial-ready is often mispriced.
If you want candidates like these, we keep a running internal list with no public URLs. Start at https://totalityestates.com/.
A word for sellers
If you hold a trophy or near-trophy asset, your advantage right now is not only price, it is process. Select the showing path, time of day matters on the water, pre-snag the obvious items, and package an information set buyers can trust: floor plans, MEP notes, insulation specs, brand and contractor details, and a clean FF&E list. The aim is to remove every reason to hesitate. If you need a discreet placement strategy, we handle that end to end at https://totalityestates.com/contact.
A risk map for 2025 to 2027, clear-eyed not alarmist
I am optimistic, not blind. Every market has moving parts, and thinking in probabilities helps.
Construction and delivery risk (low to medium impact, low to medium probability)
Off-plan luxury is better selected now, but spec drift and handover slippage still happen. The risk is rarely catastrophic, it is the small frictions: a slightly shallower balcony, a swapped appliance spec, a quarter’s delay that bumps your move-in into peak travel. Counter it by buying credible brands, checking contractor rosters, and tying variation clauses to remedies rather than apologies.
Operator and HOA risk (medium impact, medium probability)
Branded residences live or die on operations. If the operator under-delivers, or service charges creep without transparency, effortless living becomes effortful. Counter it by reading the management-agreement summaries, asking for historical service-charge schedules, and talking quietly to existing residents about response times and preventive maintenance.
Oversupply pockets (medium to high impact, low to medium probability for prime)
Most of the supply bulge sits outside true-prime. It can still matter indirectly through sentiment and headlines, but waterfront villas, prime golf frontage and line-of-sight penthouses stay insulated. Counter it by modelling for concessions and longer lease-up if you chase yield in non-prime apartments during heavy delivery windows.
Policy tweaks and macro shocks (medium to high impact, low probability)
Short-stay rules can tighten at the margin, and a global risk-off episode can pause discretionary buying. Dubai has been pragmatically pro-investment, but prudence means cash buffers and a Plan B on timelines. Counter it by keeping liquidity, avoiding over-leverage, and diversifying operators or channels if you rent.
Interest-rate sensitivity (medium impact, medium probability for leverage)
Prime buyers skew cash, but financing is growing. If you are using leverage, stress-test at plus 200 basis points and make sure your thesis does not depend on an immediate refinance to work.
A yield playbook for luxury rentals, without turning your home into a hotel
Luxury rentals run in three lanes: executive long-stay, seasonal short-stay, and hybrid at 90 to 180 days. The property’s DNA should pick the lane, not the mood of the market.
Lane 1: executive long-stay (12 to 24 months)
Who it suits: golf-front villas, quiet-stack penthouses, family-ready homes near schools and hospitals.
What wins: impeccable maintenance, blackout in the bedrooms, robust Wi-Fi, storage, easy two-car access.
Underwrite: 9 to 12 months effective occupancy with a modest void between tenants, and lower wear and tear.
Operator choice: boutique corporate-housing specialists or in-house management.
Reality check: the best long-stays are almost boring, and that is a compliment.
Lane 2: seasonal short-stay (3 to 30 nights)
Who it suits: waterfront and skyline showpieces with instant-postcard photos.
What wins: editorial-grade furnishing, concierge tie-ins, smooth entry, bulletproof cleaning.
Underwrite: rate volatility around festivals, conferences and school breaks. Model a conservative ADR and assume maintenance capex.
Operator choice: proven luxury-focused agencies with hotel-standard housekeeping.
Reality check: photos sell the booking, operations earn the reviews and the repeat direct bookings.
Lane 3: hybrid (90 to 180 days)
Who it suits: secondary homes you personally use across a season.
What wins: clear owner calendars, pre-blocked deep cleans, secure owner storage.
Underwrite: lower annual yield than pure short-stay, higher than long-stay, and less wear than nightly.
Operator choice: boutique firms that can pivot between corporate and seasonal calendars.
Operator agreement essentials
| Clause | Why it matters | Quick tip |
|---|---|---|
| Service scope and SLAs | Defines standards: response times, linens, preventive maintenance | Tie SLAs to small credits if missed |
| Fee structure | Commission versus base plus uplift, plus marketing costs | Compare net to owner, not the headline % |
| Owner use and blackout | Prevents calendar friction | Pre-block peak weeks early |
| Damage and insurance | Clarifies responsibility | Require evidence of guest and operator coverage |
| Reporting cadence | Cash clarity and trust | Monthly owner statements plus a quarterly ops review |
If you want introductions to proven luxury operators, we keep a short list by property type at https://totalityestates.com/contact.
Three compact case studies (names and details anonymised)
Case A: Palm Jumeirah, mid-frond, renovated (ready)
Profile: end-use family relocating from Europe, wanting water plus daily practicality.
Asset: 5-bed villa, mid-frond orientation, recent design-led renovation.
Why it won: terrace depth and the sunrise aspect beat larger but noisier alternatives.
Outcome: closed below guide after pre-snag, moved in 45 days later. Lasting value in livability and school-access timing.
Case B: branded urban penthouse, Downtown (ready)
Profile: global couple with two other branded homes in NYC and Singapore, needing service consistency.
Asset: corner-line penthouse, unobstructed sightline, run by a top-tier operator.
Why it won: lift ratios, separate service circulation, and amenity zoning (a quiet pool kept apart from the event deck).
Outcome: a premium over unbranded stock, justified by lower hassle and a clean exit audience.
Case C: golf-front villa, Dubai Hills (light works)
Profile: family office buying for yield plus six weeks of own use a year.
Asset: developer-standard interiors, strong bones, underwhelming lighting.
Why it won: we priced a 60-day works program (lighting, millwork, kitchen refresh) that lifted rental ADR and the photos.
Outcome: a higher net than plug-and-play comps, and the client kept a selected calendar for family weeks.
If you want the deeper numbers or the before-and-after photos, request a private pack at https://totalityestates.com/.
What to bring to a prime viewing (yes, really)
- A phone decibel app for corridors, bedrooms and the balcony.
- A laser measurer to verify ceiling heights and terrace depths.
- A compass or solar app for sun paths and glare hours.
- A white-noise file to simulate kids sleeping with the doors closed.
- A small marble to check floor evenness. Low-tech, surprisingly useful.
If a sales agent laughs at the marble, keep rolling it.