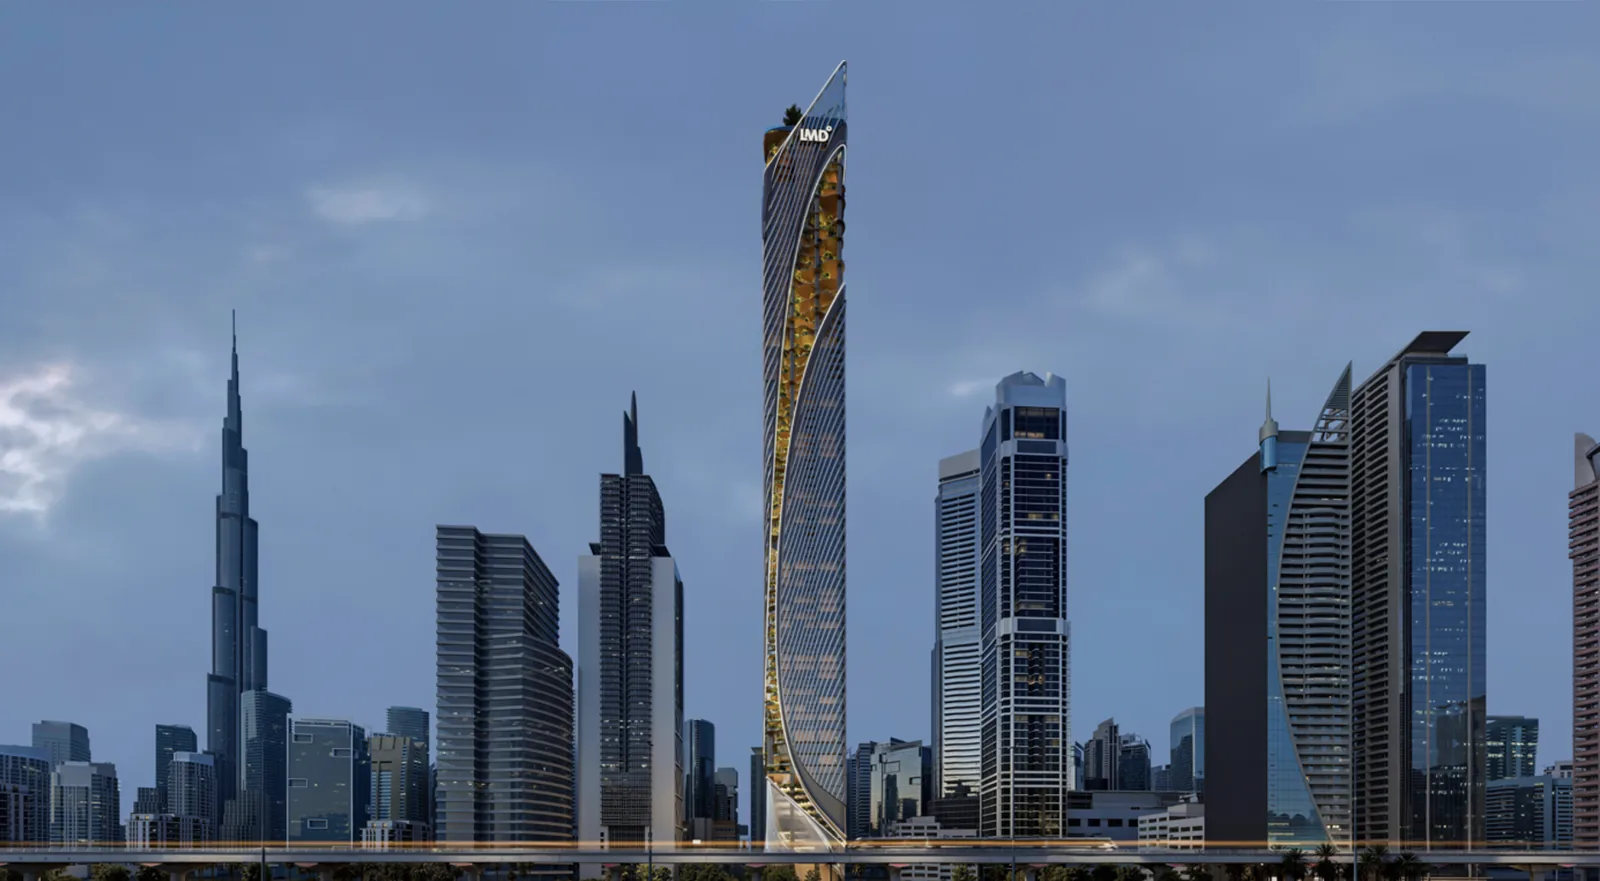
Grade A off-plan offices are selling fast. Here is how to tell the towers worth owning from the ones that only sell well.
In the first six months of 2026, buyers in Dubai paid AED 13.1 billion for offices that do not exist yet. That is more than the off-plan office market recorded in the previous seven years combined. Towers sell out on launch day, and a new one seems to be announced every week on Sheikh Zayed Road.
My clients are bullish on Grade A off-plan offices. Most of them are not seeing the big picture.
The demand is real. Vacancy in Dubai’s best office buildings is close to zero, and companies are still arriving. But prices for new offices have run well ahead of the rents those offices will earn, the brochures fill the gap with rent assumptions that today’s market does not support, and a large wave of new supply lands in 2028 and 2029, exactly when most of today’s launches hand over.
My position is simple. Buy with caution, and with a clear plan for how you will use or exit the office. With the right plan, the right building and the right purchase price, I am bullish. Without all three, a Grade A office is an expensive way to own a shell.
This guide covers the market, the real costs, what rents look like once you strip out the marketing, what to be careful of, how to pick a project, and a side-by-side of the two towers my clients ask about most: Berkeley Tower by Ellington and the Christian A. Rockefeller Business Tower by LMD.
On this page
- The commercial market in 2026
- Why offices went off-plan
- Offices, shops and warehouses
- Where to buy
- Off-plan vs ready offices
- The 2026 launch pipeline
- What a Grade A office really costs
- Rental speculation vs reality
- Financing a purchase
- Ownership, tax and visas
- What to be cautious about
- How to pick the best project
- Berkeley vs Rockefeller
- Beyond Dubai
- Frequently asked questions
Key takeaways
- Off-plan offices took 80% of Dubai’s office sales value in the first nine months of 2026, AED 16.1 billion of AED 20.16 billion.
- Grade A vacancy is 4.2% and prime availability 0.7%, but average rents have been flat since the second quarter, at about AED 241 per sq ft.
- New Business Bay off-plan offices sell for roughly AED 4,300 to 6,900 per sq ft. Ready offices in the same district averaged about AED 2,517.
- Brochure models assume AED 450 per sq ft in rent. At today’s average rent, the same office yields about 3.5% net, not 7%.
- Strata offices make up 86% of new supply in 2028 and 78% in 2029. Thousands of small units will compete for tenants at the same time.
Dubai’s commercial property market in 2026
The headline numbers explain why every developer in the city now has an office tower in its pipeline.
According to an analysis of Dubai Land Department transactions by Al Masdar Al Aqaari, developers sold 1,668 off-plan office units worth AED 13.1 billion in the first half of 2026. Between 2019 and 2025, off-plan office sales totalled AED 5.48 billion across 1,821 deals. Business Bay alone took AED 6.8 billion, about 52% of the value.
By the end of September, total office sales had reached AED 20.16 billion across 3,695 transactions, with off-plan accounting for 80% of the value and 64% of the deals.
The reason is supply. JLL put citywide office vacancy at 6.1% in the second quarter, down from 7.7% a year earlier. Grade A vacancy was 4.2% and prime availability just 0.7%. CBRE reported average rents up 13% year on year and prime rents up 16%, with occupancy around 94%. If you want a full floor in DIFC or One Central today, you are negotiating off-market or pre-leasing a building that is still under construction.
That is the bullish half. The other half gets less attention.
Savills recorded the second quarter of 2026 as the first quarter without rental growth since the first half of 2021, with the average office rent at AED 238 per sq ft. In the third quarter it held at about AED 241. Rents have not fallen, but the double-digit run has paused.
Sales cooled too. CRC Property counted 1,123 office transactions in the third quarter, 11.7% more than the second quarter, but the total value fell 42% to AED 4.35 billion. The average ticket dropped to about AED 3.87 million. Value was still 40.4% higher than a year earlier, so this is not a collapse. It is a market where smaller buyers are now doing more of the buying, and where the very large cheques of the first half have thinned out.
| Indicator | Latest figure | Source |
|---|---|---|
| Off-plan office sales, H1 2026 | AED 13.1bn, 1,668 units | Al Masdar Al Aqaari, DLD data |
| Office sales, Jan to Sep 2026 | AED 20.16bn, 3,695 deals, 80% off-plan by value | DLD data |
| Q3 2026 office sales | 1,123 deals, AED 4.35bn (-42% QoQ, +40.4% YoY) | CRC Property |
| Vacancy, Q2 2026 | 6.1% citywide, 4.2% Grade A, 0.7% prime | JLL |
| Rent growth, Q2 2026 | +13% average, +16% prime, year on year | CBRE |
| Average office rent, Q3 2026 | about AED 241 per sq ft, stable | Savills |
Why offices went off-plan
For about fifteen years, Dubai did not build a new generation of office buildings. The residential market went through a full reset, with new architecture, new amenities and new standards. Offices did not. Much of the stock companies lease today was designed before 2010.
Then demand arrived. Company formation hit records, regional headquarters moved in, and the small amount of modern Grade A space filled up. Occupiers who wanted quality had nowhere to go, and investors noticed.
In the first quarter of 2026, off-plan office sales overtook ready office sales for the first time since the third quarter of 2010, according to Cavendish Maxwell. By value the shift was even sharper: off-plan office transactions reached AED 6.4 billion in that quarter, 760% more than a year earlier.
One detail matters more than the totals. Five developments accounted for 71.7% of off-plan office sales value in the first half of 2026. This is not a broad market in which thousands of buildings trade. It is a handful of towers, bought mostly by investors, priced against each other. When five projects set the price level, “the market” is a smaller and more fragile thing than the headlines suggest.
Offices, shops and warehouses compared
Most commercial property investors in Dubai are buying offices right now, but they are not the only option.
Scroll to see all columns →
| Asset | Typical entry ticket | What drives returns | Main risk |
|---|---|---|---|
| Grade A office, off-plan | AED 4.5M and up | Rent growth to handover, resale price | Rent assumptions, 2028 to 2029 supply |
| Ready office | AED 1M to 10M+ | Rent from day one | Older stock losing tenants to new buildings |
| Retail unit | AED 1.5M to 15M | Footfall, tenant quality | Tenant turnover, location sensitivity |
| Warehouse | AED 1.5M to 10M+ | Logistics demand, low vacancy | Narrow buyer pool, slow resale |
Warehouses have the strongest rental momentum of any commercial segment. Cavendish Maxwell found warehouse rents up 12.4% year on year in the first half of 2026, with every location it monitors higher than a year earlier. Chestertons puts industrial yields in Dubai Industrial City and National Industries Park at 8% to 9%. The catch is liquidity. The buyer pool for a warehouse is small and specialised, and resale can take months. New warehouse leases also fell 51.8% in the first half as occupiers stayed put, so the next leg of rental growth depends on renewals.
Retail is more mixed. Retail rents rose 4.4% in the first half, but second-quarter sales fell sharply on the quarter. Community and street retail in dense residential districts has been the most stable. Mall units depend heavily on the operator.
Offices are where the volume is, and where the pricing has moved furthest from the income. That is why most of this guide is about them.
Where to buy commercial property in Dubai
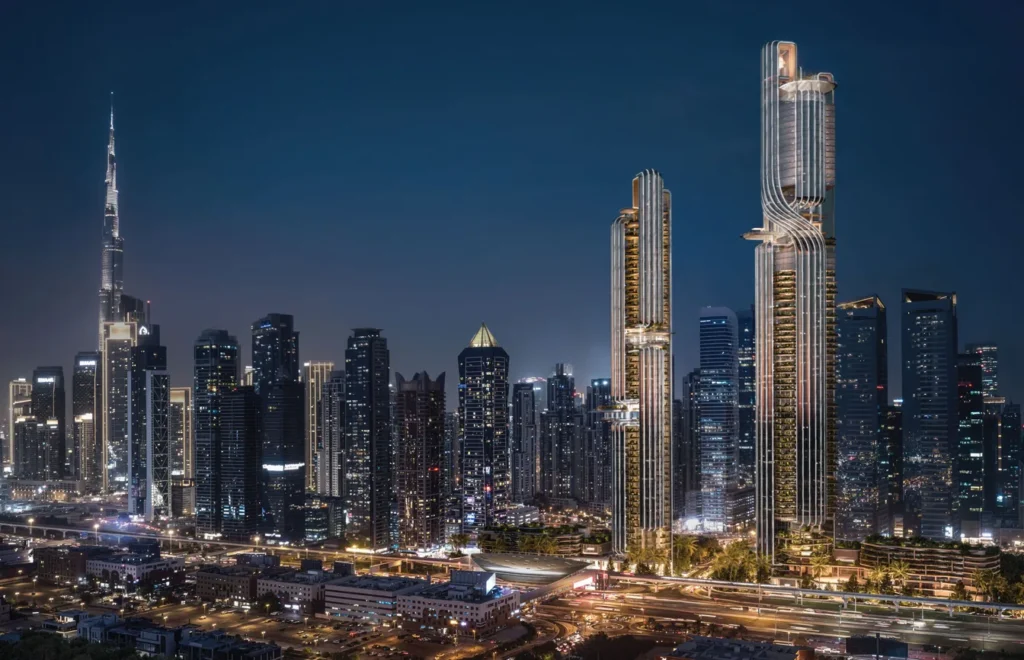
Location in commercial property is more literal than in residential. A tenant pays for a two-minute walk to the metro, a short drive to the client, and an address that signals something to their own customers.
- Business Bay. The centre of the off-plan wave, with 814 office sales in the first half of 2026, more than any other district. Freehold, mainland, a minute from Downtown and DIFC. Quality varies enormously from tower to tower, which is both the opportunity and the trap.
- Sheikh Zayed Road and Downtown. The established corporate spine. Boulevard Plaza and Emaar Square are the benchmarks for Downtown rents, and new launches like the Rockefeller tower and AHS Twin Towers are priced off this address.
- DIFC. The tightest market in the city, and the one with the highest rents. Very little new DIFC office space is sold to private investors in small units, so for most buyers this is a leasing market, not an ownership one.
- JLT and Al Sufouh (Media City, Internet City). Large established office clusters with deep tenant demand and lower entry prices than Business Bay. Al Sufouh 1 was the second-busiest office sales district in the first half.
- Downtown Jebel Ali and Dubai South. Downtown Jebel Ali was the busiest office market by transaction count in the third quarter, according to CRC Property. Lower prices, longer horizon, tied to the Al Maktoum airport and Jebel Ali port story.
- The Sheikh Mohammed Bin Zayed Road corridor. New mixed-use communities like The Yards in City of Arabia are bringing office stock to suburban locations at roughly half the price per sq ft of Business Bay. Cheaper entry, but untested office demand.
Business Bay office towers: what they trade at
Scroll to see all columns →
| Tower | Status | Price per sq ft (AED) | Notes |
|---|---|---|---|
| Vision Tower | Ready (2011) | 3,150 to 4,678 | DLD median by month, Nov 2025 to Jul 2026 |
| Anantara Downtown Business Tower | Ready | about 6,000 asking | One furnished listing; fitted rents AED 246 to 350 |
| Burj Capital | Off-plan, Q4 2028 | about 3,500 to 3,800 | Broker listings, shell and core |
| Berkeley Tower | Off-plan, 2030 | about 4,300 | Current guidance, varies by floor and buyer |
| HQ by Rove | Off-plan, Q1 2029 | about 4,760 | Index price on 311 registered sales; small fitted units |
| Lumena | Off-plan | about 5,200 to 6,100 | DLD transactions |
| Lumena Alta | Off-plan, 2030 | about 6,050 to 6,950 | DLD transactions |
The spread inside one district is the point. A buyer at AED 6,500 per sq ft and a buyer at AED 3,600 per sq ft are both “buying Grade A in Business Bay”. They will not earn the same return.
Off-plan vs ready offices
Ready offices in Business Bay averaged about AED 2,517 per sq ft between January and May 2026. One analysis of DLD data put the middle price of new Business Bay off-plan offices at about AED 4,870 for January to July. That is a premium of roughly 93% for a building that does not exist yet.
Citywide, Cavendish Maxwell put the average office sale price at AED 2,012 per sq ft in the first half of 2026, up 15% on a year earlier.
Part of that premium is earned. A new building has better lifts, better floor plates, better parking, green certification and a payment plan that spreads the cost over four or five years. Large occupiers are increasingly refusing to lease older stock at all, and older buildings will need capital spent on them to compete.
Part of it is not earned. Some of the premium is the brochure, the brand on the tower and the momentum of the last eighteen months.
A ready office makes more sense when you want income now, when you are buying for your own company and need the space before 2029, or when you can buy a good unit in an older building below replacement cost and refurbish it. An off-plan office makes sense when you want a modern building in a location that will still be prime in 2030, you can carry the payments without stress, and the price per sq ft holds up against what similar new offices are transacting at, not what they are being advertised at.
The 2026 Grade A launch pipeline
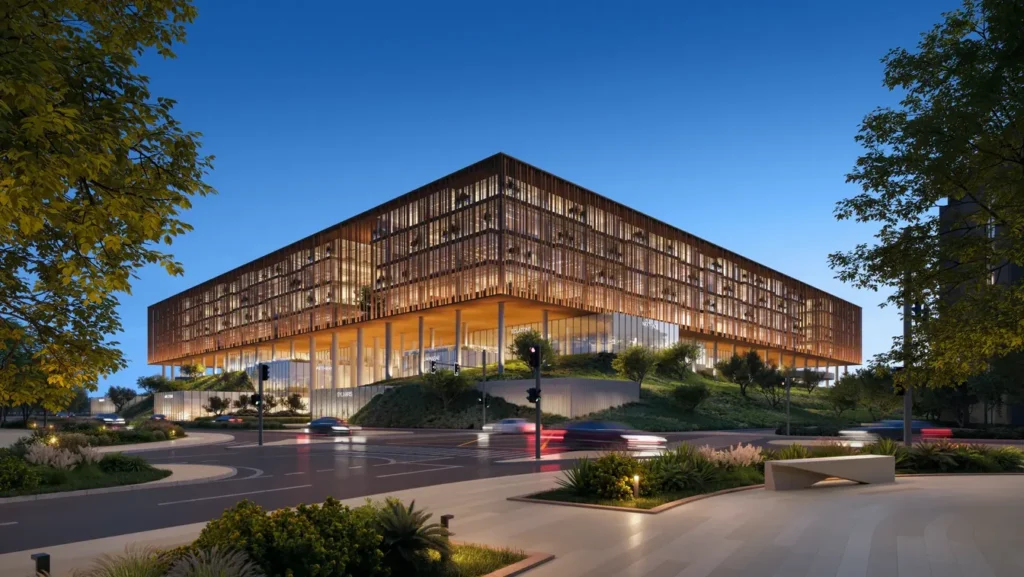
Scroll to see all columns →
| Project | Developer | Location | Price per sq ft (AED) | Plan | Handover |
|---|---|---|---|---|---|
| Berkeley Tower | Ellington Properties | Business Bay | about 4,300 | 50/50 | 2030 |
| Christian A. Rockefeller Business Tower | LMD | Sheikh Zayed Road | about 4,600 (5% off first 100 units) | 50/50 | Q2 2031 |
| The Yards Plaza | Beyond (Omniyat Group) | City of Arabia | about 2,200 (from AED 2.85M) | 40/60 | Q3 2029 |
| Lumena Alta | Omniyat | Business Bay | about 6,050 to 6,950 transacted | 50/50 | 2030 |
| AHS Twin Towers | AHS Properties | Sheikh Zayed Road | reported from about 4,000 | TBC | TBC |
| HQ by Rove | IRTH | Business Bay | about 4,760 transacted | 50/50 | Q1 2029 |
| 1970 Office Tower | Al Habtoor Group | Al Habtoor City | from 5,000 | 60/40 | Q1 2029 |
| Burj Capital | Centurion (OCTA) | Business Bay | about 3,500 to 3,800 listed | 50/50 | Q4 2028 |
| Eaton Square | Ellington Properties | MBR City | from about 3,300 at launch | 70/30 | Q2 2028 |
A few things stand out.
The launches have moved up in price fast. Ellington’s first office building, Eaton Square, launched at around AED 3,300 per sq ft. Its second, Berkeley Tower, is guided at around AED 4,300, roughly 30% higher about a year later.
Handover dates cluster. Most of these buildings complete between Q4 2028 and Q2 2031. If you buy into any of them, your tenant search starts at the same moment as hundreds of other owners in the towers next door.
AHS Twin Towers is a conversion, not a new build. AHS bought the Shangri-La Dubai for AED 1.1 billion and is turning it into a USD 1.3 billion Grade A office project of about 1 million sq ft. Conversions can deliver faster, but the floor plates and core were designed for a hotel, so check them carefully.
What a Grade A office really costs
The price on the brochure is the start of the bill, not the end of it.
Scroll to see all columns →
| Cost | Amount | Who pays and when |
|---|---|---|
| DLD registration fee | 4% of the price | Buyer, at booking |
| VAT | 5% of the price | Paid with each instalment, not upfront. Recoverable as input tax for a VAT-registered company. A cost for an individual. |
| Service charge | AED 18 to 24 per sq ft a year on the current launches | Owner, from handover, whether or not the office is let |
| Fit-out | roughly AED 300 to 550 per sq ft for a standard to mid-range office, far more at the top end | Owner or tenant, after handover |
| Letting fee | 5% to 10% of the first year’s rent | Owner, each time the office is let |
| Exit costs | brokerage of about 2% plus VAT on resale | Seller |
Two of these deserve more than a line.
VAT. Commercial property in the UAE carries 5% VAT, which residential buyers are not used to. It is paid in step with the payment plan, so on a 50/50 plan you pay 2.5% of the price before completion and 2.5% at handover. Whether you get it back depends on how you buy. A VAT-registered company that uses or leases the office can claim it back as a credit. An individual cannot. I come back to this in the section on ownership, because it is also the line between getting a Golden Visa and not getting one.
Fit-out. Every one of the big launches is sold shell and core. You receive the structure, facade, lifts and building systems, and nothing else: no ceilings, no floors, no partitions, no pantry. Market guides put a standard Dubai office fit-out at roughly AED 280 to 380 per sq ft and a mid-range Grade A fit-out at AED 400 to 650. Turner & Townsend’s medium-specification average for Dubai and Abu Dhabi works out at around AED 1,030 per sq ft, because it includes a fuller scope. Either the owner pays for this, or the tenant does and expects a rent-free period or a lower rent in return. It never disappears.
Worked example: a 2,650 sq ft office at AED 4,300
This is an illustration on round numbers at Berkeley Tower’s current guidance, on a 50/50 plan, bought by an individual. It is not a price list or an offer.
| Item | AED |
|---|---|
| Purchase price (2,650 sq ft x 4,300) | 11,395,000 |
| DLD fee (4%) | 455,800 |
| VAT (5%), not recoverable for an individual | 569,750 |
| Basic shell and core fit-out (AED 350 per sq ft) | 927,500 |
| All-in cost | 13,348,050 |
| All-in cost per sq ft | 5,037 |
| Annual service charge (AED 24 per sq ft) | 63,600 |
The AED 4,300 office actually costs just over AED 5,000 per sq ft by the time it can be let. A VAT-registered company buying the same unit would pay about AED 12.78 million all-in, or AED 4,822 per sq ft, because the VAT comes back.
Cash flow on the 50/50 plan looks like this for the individual: about AED 6.44 million before completion (half the price, the DLD fee and half the VAT), then about AED 5.98 million at handover, plus the fit-out. If the plan is to fund the handover payment with a bank loan, remember that lenders value the finished building, not the price you agreed in 2026.
Rental price speculation vs reality
This is the section most brochures skip, and it decides whether an office investment works.
What the brochures assume
Developer models for the current Grade A launches use rents of around AED 450 per sq ft a year. Some comparison slides in marketing decks show neighbouring towers at AED 490 to 594. On those numbers, a Business Bay office bought at AED 4,300 earns a gross yield of about 10%, and the investment case looks easy.
What the market shows
| Rent benchmark | AED per sq ft a year |
|---|---|
| Citywide average office rent, Q3 2026 (Savills) | about 241 |
| Grade A asking rents in Business Bay, October 2026 | 260 to 375 |
| Anantara Downtown Business Tower, fitted and furnished asking | 246 to 350 |
| Large Business Bay floors, 12,000 to 14,000 sq ft, asking | roughly 200 to 250 |
| Vision Tower, fully fitted full floor, asking | about 650 |
| Boulevard Plaza and Emaar Square, Downtown, asking | roughly 370 to 490 |
The AED 450 to 594 figures are real asking rents. They are also, almost without exception, rents for fitted and furnished space in established buildings, often for small units. A tenant paying AED 650 for a fitted floor in Vision Tower is paying for the fit-out, the furniture and the move-in date as much as the space.
The towers being sold today hand over as empty shells. A shell-and-core floor lets for less than a fitted one, or the landlord pays for the fit-out to achieve the higher rent. Applying a fitted, furnished, small-unit asking rent to a shell-and-core purchase is the single biggest overstatement in the current wave of office marketing.
There is also a gap between asking rents and what tenants actually sign. One analysis of DLD lease data put the median transacted office rent in Business Bay at about AED 148 per sq ft, across all grades of stock. New Grade A space will lease far above that, but it shows how much of the market sits well below the brochure.
What different rents do to your return
Same assumptions as the developer models: 90% occupancy, 15% for letting costs, voids and management, and the service charge deducted. Yields are on the purchase price plus the 4% DLD fee, and for individuals plus the 5% VAT. Fit-out is excluded, which flatters every number in the table.
Scroll to see all columns →
| Rent (AED per sq ft) | Berkeley at 4,300, company | Berkeley at 4,300, individual | Rockefeller at 4,600, company | Rockefeller at 4,600, individual |
|---|---|---|---|---|
| 450 (brochure) | 7.2% | 6.8% | 6.8% | 6.5% |
| 375 (top of Business Bay asking) | 5.9% | 5.6% | 5.6% | 5.4% |
| 300 | 4.6% | 4.4% | 4.4% | 4.2% |
| 241 (citywide average) | 3.6% | 3.4% | 3.5% | 3.3% |
Company yields are before corporate tax. At the Rockefeller tower’s 5% early-buyer discount, its yields move almost exactly into line with Berkeley’s. Add a basic AED 350 fit-out at AED 300 rent and the Berkeley yield falls to about 4.3% for a company and 4.1% for an individual.
The brochure case needs the office to let at AED 450 shell and core in 2030. From today’s citywide average of AED 241, that is rent growth of about 17% a year for four years. From AED 300, it is about 11% a year. Possible in a supply-starved market. Not something to underwrite as the base case when 2028 and 2029 bring the biggest wave of new office space in years.
My rule is to underwrite an off-plan office on a rent you could sign a tenant at today for comparable new space, then treat rent growth as upside. If the deal only works at the brochure rent, it is not a deal.
If a tower only works at the brochure rent, you want to know before you sign.
Let Ber show you what developers don’t.
Before you commit AED 5 million or more to an office that won’t exist until 2030, sit down with Ber Mitchell. He puts the brochure next to the DLD record: what the last buyer actually paid, what the floor will realistically lease for shell and core, and the costs that never make it into the deck. 25 years and about USD 3 billion in cross-border deals.
Financing a commercial purchase
Most buyers fund an off-plan office in cash until completion. Bank appetite for lending against an unfinished commercial unit is limited, and where it exists it comes with conservative terms.
Once the building is complete and the title is issued, finance becomes more realistic. In my experience most banks lend 50% to 75% of value on completed offices, depending on the building, the borrower and whether the office is let. The bank values the finished unit itself. If the market price of comparable offices in 2030 is below what you agreed in 2026, the loan is sized on the lower number and the gap comes from your pocket.
If your plan depends on a mortgage at handover, get a conversation with a lender started early, and model the handover payment at 50% LTV, not 75%.
Ownership, tax and visas
Business Bay, Downtown, Sheikh Zayed Road freehold plots, JLT and the other designated freehold areas allow foreign individuals and approved companies to own offices outright. The choice that matters is whether you buy in your own name or through a company, because it changes three things at once.
| Buy personally | Buy through a company | |
|---|---|---|
| 5% VAT | A real cost, not refundable | Recoverable as input tax if the company is VAT-registered and uses or leases the office |
| Golden Visa | Eligible at AED 2 million or more | Not eligible on the property |
| Tax on rental profit | Individuals holding property in their own name are generally outside UAE corporate tax | 9% corporate tax on taxable profit above AED 375,000 |
Golden Visa. The property route requires an asset worth AED 2 million or more. Since early 2026, off-plan purchases qualify on the full contract value registered on Oqood, without the old requirement to have paid half. Every office in the towers discussed here is above that threshold. Sources do not agree on how consistently commercial units are accepted, so confirm with the Dubai Land Department that your specific unit qualifies before you rely on it.
The trade-off. On an AED 11.4 million office, the VAT is about AED 570,000. A company gets that back. An individual pays it but can apply for a ten-year visa for the family. Neither is automatically the right answer. Decide which you need before you sign the reservation form, because changing the buyer name later costs another round of fees.
This is general information, not tax advice. Take advice on your own structure, and on how your home country taxes the income.
What to be cautious about with Grade A off-plan offices
These are the issues I raise with every client who brings me an office brochure.
The 2028 to 2029 supply wave. Savills expects about 20.4 million sq ft of new office space between 2026 and 2030, with most of it arriving from 2028. Strata-owned buildings, sold in small units to individual investors, make up 86% of new supply in 2028 and 78% in 2029. When your building hands over, so do the towers either side of it, and every owner will be looking for a tenant at once. Large corporate occupiers also tend to prefer whole floors from a single landlord, which strata towers struggle to offer.
Fitted rents applied to shell space. Covered above. Check which rent the model uses and ask who pays for the fit-out.
Appreciation assumptions. Some developer models assume 12% a year price growth for five years. Recent momentum supports strong numbers: office sale prices rose 15% year on year in the first half of 2026. The longer record is less kind. ValuStrat’s index of Dubai office capital values was still 30.3% below its 2015 level at the end of 2021, and only got back to roughly the 2015 level in the second quarter of 2023. That is about eight years without a gain. Model 5% to 7% a year as your base case and treat anything above as upside.
Prices vary between buyers. Developers are testing price levels during launches, and some offer discounts to particular buyers or early allocations. The buyer next to you may have paid less. That matters when you resell, because the resale comparables will include their price, not yours.
Payment plans vary by channel. The same tower can be sold on a 50/50 plan through one route and 70/30 through another. Ask for the plan in writing and check that it matches the SPA.
Handover dates. Check the completion date on the DLD register, through Dubai REST, and in the SPA. Marketing material and the register do not always agree, and commercial towers of 60 to 87 floors are exactly the kind of building where delays happen.
Costs residential buyers miss. VAT, limited finance before completion, service charges from day one of handover, corporate tax if you buy through a company, and fit-out.
Cooling momentum and concentrated demand. Third-quarter sales value fell 42% on the quarter. Five projects took more than 70% of off-plan value in the first half. If investor demand slows further, resale before handover gets harder, because assignment buyers are drawn from the same pool.
Track record in commercial. Both of the towers compared below are large first steps for their developers. Berkeley is Ellington’s second office building and by far its largest. Rockefeller is LMD’s first office tower in Dubai. Strong residential track records are worth a lot. They are not the same as having delivered and managed a 60-plus floor office building.
Exit before handover. Most developers allow resale once a set share of the price is paid. For the towers here that threshold is around 30%. Below it you cannot sell, whatever happens to your circumstances.
Before you commit to an office that won’t exist until 2030, get the brochure checked against the record.
Let Ber show you what developers don’t.
Before you commit AED 5 million or more to an office that won’t exist until 2030, sit down with Ber Mitchell. He puts the brochure next to the DLD record: what the last buyer actually paid, what the floor will realistically lease for shell and core, and the costs that never make it into the deck. 25 years and about USD 3 billion in cross-border deals.
How to determine the best project
Run every office you are considering through the same scorecard. The thresholds are my working rules, not market standards.
Scroll to see all columns →
| Check | Proceed | Negotiate harder | Walk away |
|---|---|---|---|
| Walking distance to metro | Under 5 minutes | 5 to 10 minutes | Car-only |
| Price vs transacted comps for new offices nearby | Below | Within 5% | Above, with no clear reason |
| All-in cost per sq ft (incl. DLD, VAT if personal, fit-out) | Supports a 5%+ net yield at today’s rents | 4% to 5% | Under 4% |
| Rent used in the developer model | Matches signed rents for comparable new space | Uses fitted rents for shell space | No rent evidence at all |
| Service charge | Under AED 20 per sq ft | 20 to 28 | Above 28, or not disclosed |
| Floor plate and layout | Efficient, column-free, divisible | Workable | Awkward shapes, deep plates |
| Lifts and parking per office | Generous, destination control | Average | Undersized for the floor count |
| Share of the tower sold to small investors | Mixed with larger floors | Mostly strata | All small strata units |
| Unit size | 1,000 to 3,000 sq ft, the most liquid band | 3,000 to 6,000 sq ft | Very small or very large with no comparables |
| Handover vs the 2028 to 2029 wave | Before 2028, or after 2030 with pre-leasing | During the wave | During the wave, no leasing plan |
| Developer delivery record | Has delivered comparable commercial buildings | Strong residential record only | Unresolved delays |
| Green certification | LEED or WELL committed | Planned | None |
| Your exit plan | Clear: occupy, lease or assign | Partly clear | “It will go up” |
Offices of 1,000 to 2,000 sq ft accounted for 53% of ready office sales in the first half of 2026, according to Cavendish Maxwell. That is the most liquid size band in the city. Full floors attract fewer buyers but better tenants. Neither is wrong, but you should know which game you are playing.
The row that kills the most deals is the third one. Work out the all-in cost per sq ft, apply a rent you can evidence today, and see what yield is left. If it is under 4%, the investment depends entirely on capital growth, and you are speculating, not investing.
Berkeley Tower vs Rockefeller Business Tower
Disclosure: Totality Real Estate markets both towers. The comparison below is built from the developers’ published information, current pricing guidance and DLD-registered data. My own view is at the end of the section.
Scroll to see all columns →
| Berkeley Tower | Christian A. Rockefeller Business Tower | |
|---|---|---|
| Developer | Ellington Properties, with Al Hamra Group | LMD, branded under Christian A. Rockefeller |
| Location | Business Bay, a minute from Business Bay Metro and Sheikh Zayed Road | Sheikh Zayed Road, between DIFC, Downtown and Business Bay |
| Height | Above 60 floors, 55 office floors | 86 floors, marketed as the city’s tallest commercial tower on completion |
| Offices | 109 | 332 |
| Entry ticket | above AED 4.5 million | above AED 4.5 million |
| Price per sq ft | about AED 4,300 | about AED 4,600, 5% discount on the first 100 units |
| Payment plan | 20% on contract plus 4% DLD; 10% at 300 days; 5% at each of 30%, 40%, 50% and 60% completion; 50% on handover | 20% on booking; 5% at 15, 21, 27, 33, 39 and 45 months; 50% on handover |
| VAT | Paid with each instalment | Paid with each instalment |
| Service charge | AED 24 per sq ft | AED 18 per sq ft (estimate) |
| Handover | 2030 | Q2 2031 |
| Lifts | 12 double-deck, destination-controlled | 23 |
| Parking | Robotic parking | 1,100+ spaces |
| Amenities | Five floors: business lounges, fitness and wellness, terraces, clubhouse | Five floors, two for health and fitness; sky business centre on level 87 |
| Project value | AED 2.8 billion | Construction cost of AED 1.1 billion stated at launch |
| Resale before handover | After 30% paid | After 30% paid |
What the data says
Density. Berkeley has 109 offices against Rockefeller’s 332. Fewer owners means fewer units competing for tenants and fewer resale listings undercutting each other in 2030. On the supply risk set out above, this favours Berkeley.
Price and running cost. At list prices Berkeley is about 6.5% cheaper per sq ft. Rockefeller’s service charge is AED 6 per sq ft lower, which on a 2,650 sq ft office is AED 15,900 a year. With the 5% early discount, Rockefeller’s price drops to about AED 4,370 and the two towers produce almost identical yields at every rent level.
Cash flow. Both are 50/50. Berkeley front-loads more: 30% within the first 300 days. Rockefeller asks for 20% at booking and then spreads 30% over nearly four years. For an investor who wants to keep capital working elsewhere for longer, Rockefeller’s plan is gentler, and its handover is a year later.
Address and brand. Rockefeller sits directly on Sheikh Zayed Road with the most recognisable name in the current pipeline. For a company that sees its office as part of its brand, that matters, and branded addresses tend to hold a premium. Berkeley’s advantage is the micro-location: next to Business Bay Metro, inside the district that carried more than half of Dubai’s off-plan office sales value this year.
Timing. Berkeley hands over in 2030, Rockefeller in 2031. Both miss the worst of the 2028 to 2029 wave, but Berkeley lands closer to it.
Who each suits, on the data alone. Berkeley suits a buyer who wants a lower entry price per sq ft, a smaller and less crowded building, and a metro-side Business Bay address, and who can carry the heavier first year. Rockefeller suits a buyer who values the Sheikh Zayed Road address and the brand, wants lower running costs, prefers a longer and gentler payment schedule, and can secure one of the first 100 units at the discount.
My view. My pick is Rockefeller, and it is the name that settles it. On price per sq ft the two sit almost level, so this is not a numbers call, it is an address call. Telling a client your office is in the Rockefeller Tower on Sheikh Zayed Road lands harder than any address in the city, and that prestige is what pulls the better tenants, the higher rent and the quicker lease. Add the tallest and most sustainable commercial tower in Dubai and you are buying an icon, not just a floor.
Deciding between two towers, or two floors in the same one?
Let Ber show you what developers don’t.
Before you commit AED 5 million or more to an office that won’t exist until 2030, sit down with Ber Mitchell. He puts the brochure next to the DLD record: what the last buyer actually paid, what the floor will realistically lease for shell and core, and the costs that never make it into the deck. 25 years and about USD 3 billion in cross-border deals.
Beyond Dubai
Abu Dhabi has the tightest office market in the UAE. JLL put citywide vacancy at 1.4% in the second quarter of 2026, with prime availability at 0.1%. Ownership opportunities for private investors in Abu Dhabi offices are fewer than in Dubai, but the occupier market is strong, and I am very bullish on Abu Dhabi more broadly.
Ras Al Khaimah’s office market is small. The investment story there is hospitality and residential around Al Marjan Island, not offices, and that is where I would look.
Frequently asked questions
Is buying an office in Dubai a good investment in 2026?
It can be, with the right building at the right price and a clear plan to occupy, lease or sell. Demand for Grade A space is strong and vacancy is low. But new off-plan offices are priced well ahead of today’s rents, and a large wave of supply arrives in 2028 and 2029. Underwrite on today’s rents, not the brochure’s.
What rental yield can a Grade A office realistically make?
At today’s rents, roughly 3.5% to 6% net on new off-plan offices bought at AED 4,300 to 4,600 per sq ft, depending on the rent achieved and whether you can recover the VAT. The 7% to 10% figures in marketing material usually assume fitted, furnished rents on space that is handed over as a shell.
Do I pay VAT on a commercial property in Dubai?
Yes, 5% of the price, paid in proportion to each instalment. A VAT-registered company that uses or leases the office can recover it. An individual cannot.
Can foreigners buy commercial property in Dubai?
Yes, in designated freehold areas such as Business Bay, Downtown, JLT and parts of Sheikh Zayed Road. You can buy in your own name or through an approved company.
Does an office purchase qualify for a Golden Visa?
The property route requires AED 2 million or more, and off-plan purchases qualify on the full Oqood value. It applies to properties held in your own name, not through a company. Confirm with the DLD that your specific commercial unit is accepted.
Off-plan or ready office: which is better?
Ready offices produce income now and cost far less per sq ft. Off-plan offices give you a modern building and a payment plan, at a premium of roughly 90% in Business Bay. If you need income or space before 2029, buy ready. If you want a new building in a location that will still be prime in 2030, and the price holds up against transacted comparables, off-plan can work.
Can I get a mortgage on an off-plan office?
Rarely before completion. Most buyers pay in cash until handover. On completed offices, most banks lend 50% to 75% of value.
What are service charges on Grade A offices?
On the current launches, AED 18 to 24 per sq ft a year. Established Downtown towers such as Boulevard Plaza run around AED 27 to 28. You pay them from handover whether or not the office is let.
When does new office supply arrive?
Savills expects about 20.4 million sq ft between 2026 and 2030, with the larger increase from 2028. Strata buildings make up most of the 2028 and 2029 deliveries.
Can I sell an off-plan office before handover?
Usually yes, once you have paid the developer’s threshold, which is around 30% for the towers in this guide. You need the developer’s NOC and pay transfer fees. Assignment demand depends on investor appetite at the time you sell.
One office, five years, several million dirhams. Worth a second opinion.
Let Ber show you what developers don’t.
Before you commit AED 5 million or more to an office that won’t exist until 2030, sit down with Ber Mitchell. He puts the brochure next to the DLD record: what the last buyer actually paid, what the floor will realistically lease for shell and core, and the costs that never make it into the deck. 25 years and about USD 3 billion in cross-border deals.
Not financial advice. Do your own research. This guide is general information, not legal, tax or financial advice. Prices, payment plans, discounts and developer terms change and vary by unit and buyer. Yield and cost examples are illustrations built on stated assumptions, not forecasts or offers. Verify every figure against the SPA, the developer’s current price list and DLD records, and take independent advice on tax and structure. Totality Real Estate markets Berkeley Tower and the Christian A. Rockefeller Business Tower.
Sources: Gulf Business: off-plan office sales H1 2026 · Khaleej Times: off-plan office sales H1 2026 · Khaleej Times: Q3 2026 office sales, CRC Property · Khaleej Times: JLL UAE Market Dynamics Q2 2026 · Arab News: CBRE UAE Q2 2026 · Savills Dubai Office Q2 2026 · Savills Dubai Office Q3 2026 · Savills Q3 2026 pipeline · Cavendish Maxwell: office sales Q1 2026 · Khaleej Times: office sales H1 2026, Cavendish Maxwell · Built Environment ME: office supply pipeline · ValuStrat Q2 2023 report · Off-plan vs ready offices, DLD analysis · Business Bay office prices and rents 2026 · Propsearch: Lumena transactions · Propsearch: Lumena Alta transactions · Property Index: HQ by Rove · Vision Tower registered prices · JLL: Vision Tower full floor · Anantara Business Tower rents · Ellington: Berkeley Tower launch · Arabian Business: Rockefeller Business Tower · Rockefeller Business Tower fact sheet · TradeArabia: The Yards Plaza · AHS Twin Towers announcement · 1970 Office Tower · Burj Capital listing · Eaton Square · Turner & Townsend fit-out cost guide 2026 · Dubai fit-out cost benchmarks 2026 · UAE Golden Visa 2026 · Golden Visa off-plan rule change 2026 · Cavendish Maxwell retail and warehouse H1 2026 · Chestertons: industrial warehousing 2026
Totality Real Estate | RERA licensed